
28 August 2019
Is a House always “Residential Property” for SDLT?
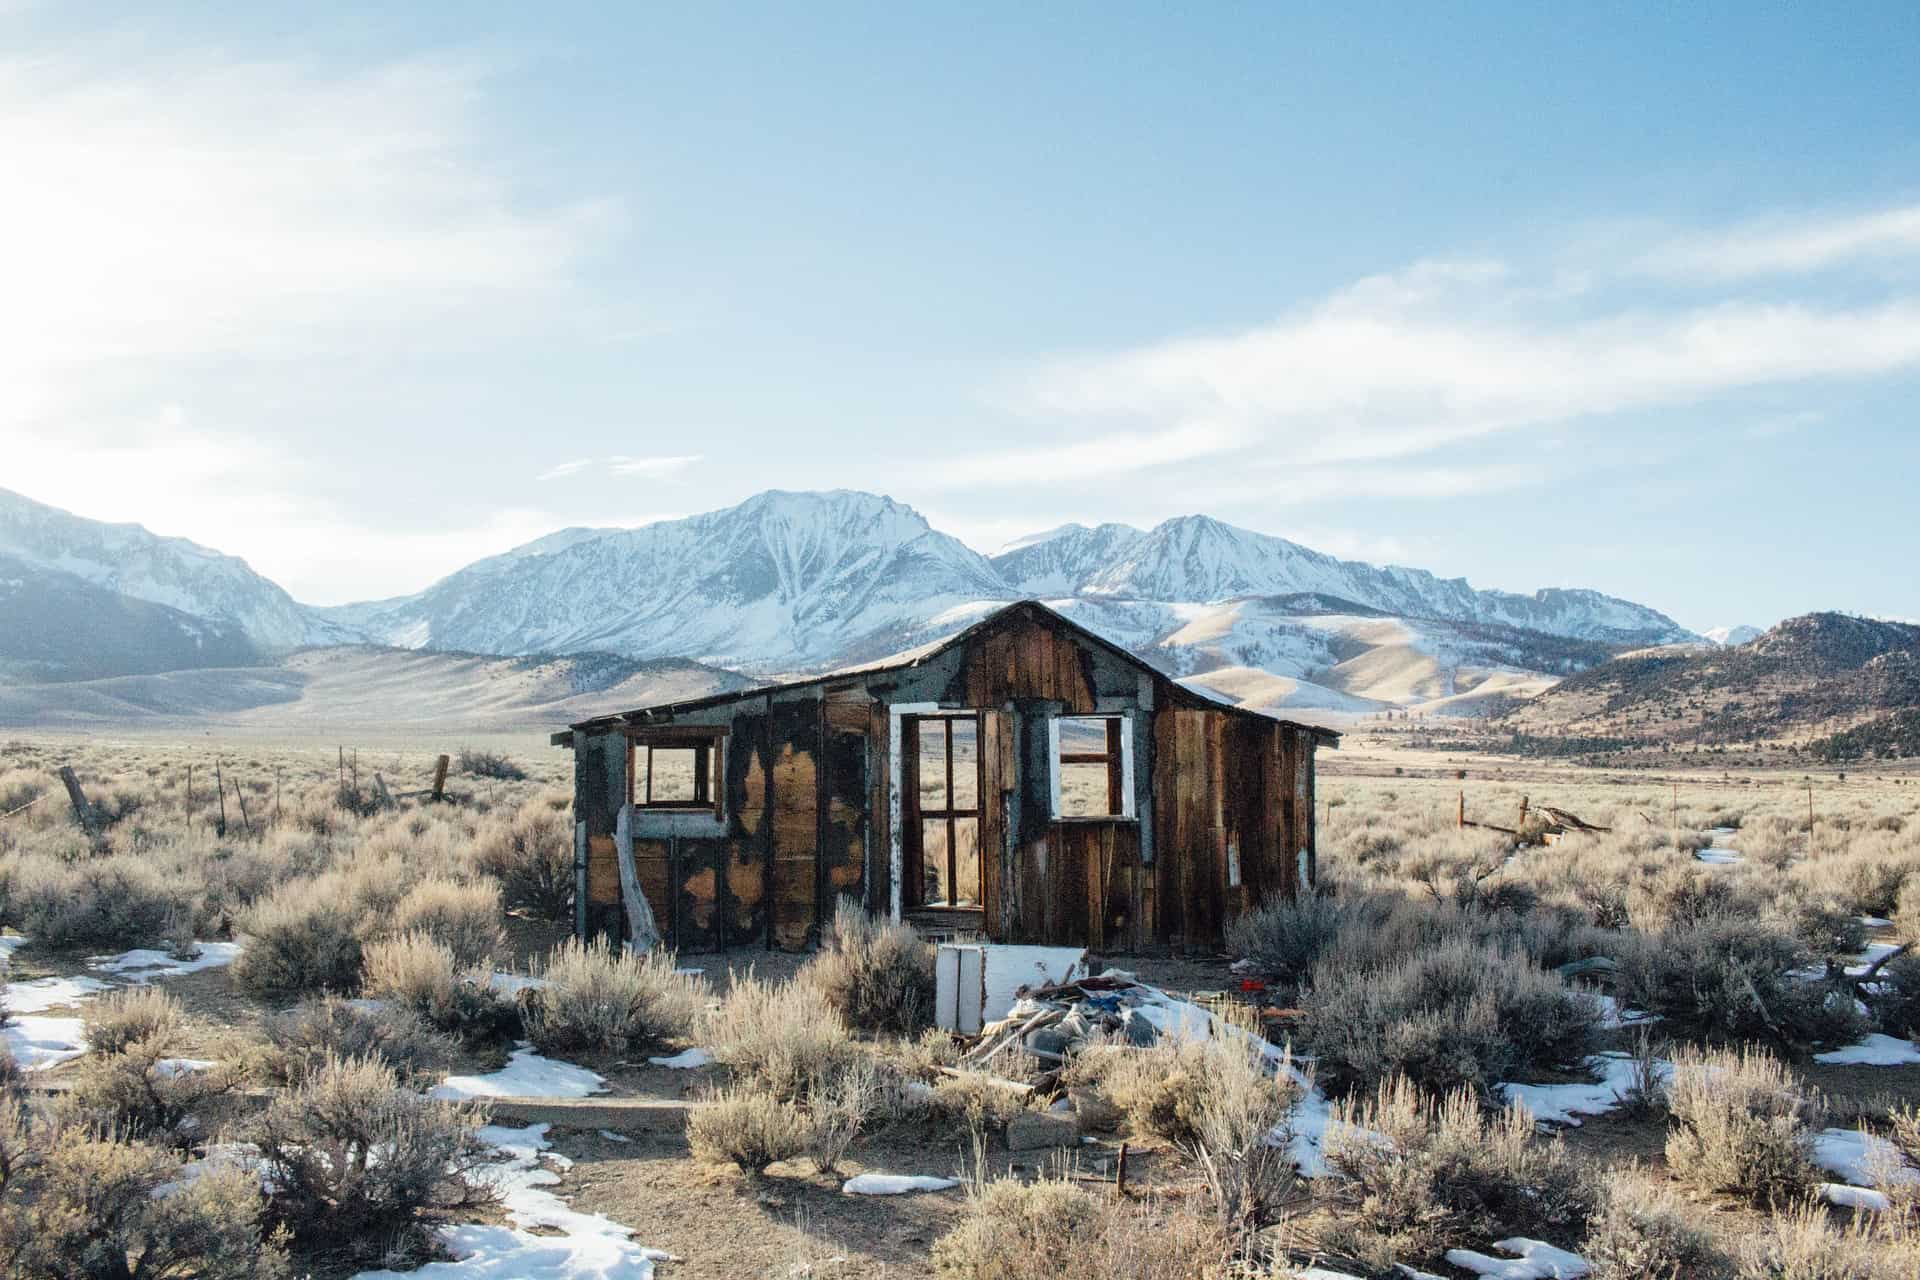
Stamp Duty Land Tax ("SDLT") is payable by the buyer on the purchase of land and property in England and Northern Ireland.
The rate at which SDLT is charged is determined by whether or not the property is "residential" property, which is defined in the legislation as a building that is:
- Used or suitable for use as a dwelling; or
- In the process of being constructed or adapted for such use.
- Prior to purchase, P N Bewley Ltd ("PNB") commissioned a demolition survey for a delapidated house where it was found that the property contained asbestos-containing materials and the heating system had been removed. The survey itself was described as a disruptive and fully intrusive survey that involved destructive application techniques, including breaking into floors, walls, and ceilings.
- PNB purchased the house for £200,000 and applied the SDLT rates for non-residential property on the basis that it was not capable of being used as dwelling due to its poor state of repair, and was unviable as a renovation or refurbishment project as this would disturb the asbestos.
- HMRC disagreed with PNB's treatment of the property and re-calculated the SDLT on the basis that the property was a residential property.
- The term "dwelling" does not require the property to be mortgagable, meet the better homes standard, or to be of standard construction, and a dwelling does not change its nature because it falls into dilapidation.
- The property was a residential plot in a residential area, and the intention was for the plot to continue to be a residential plot comprising a dwelling and its grounds.
- The fact that a buyer could not be found to refurbish the property did not mean that it ceased to be a dwelling, or that it was not capable of being renovated and occupied as a dwelling.
- The presence of asbestos in the existing building did not prevent its renovation or reoccupation, as the critical risk would come during demolition.